The water damage insurance claim checklist: the first 48 hours
What you do before the adjuster calls back decides how the claim goes. Eight steps, in order - most of them in the first day.
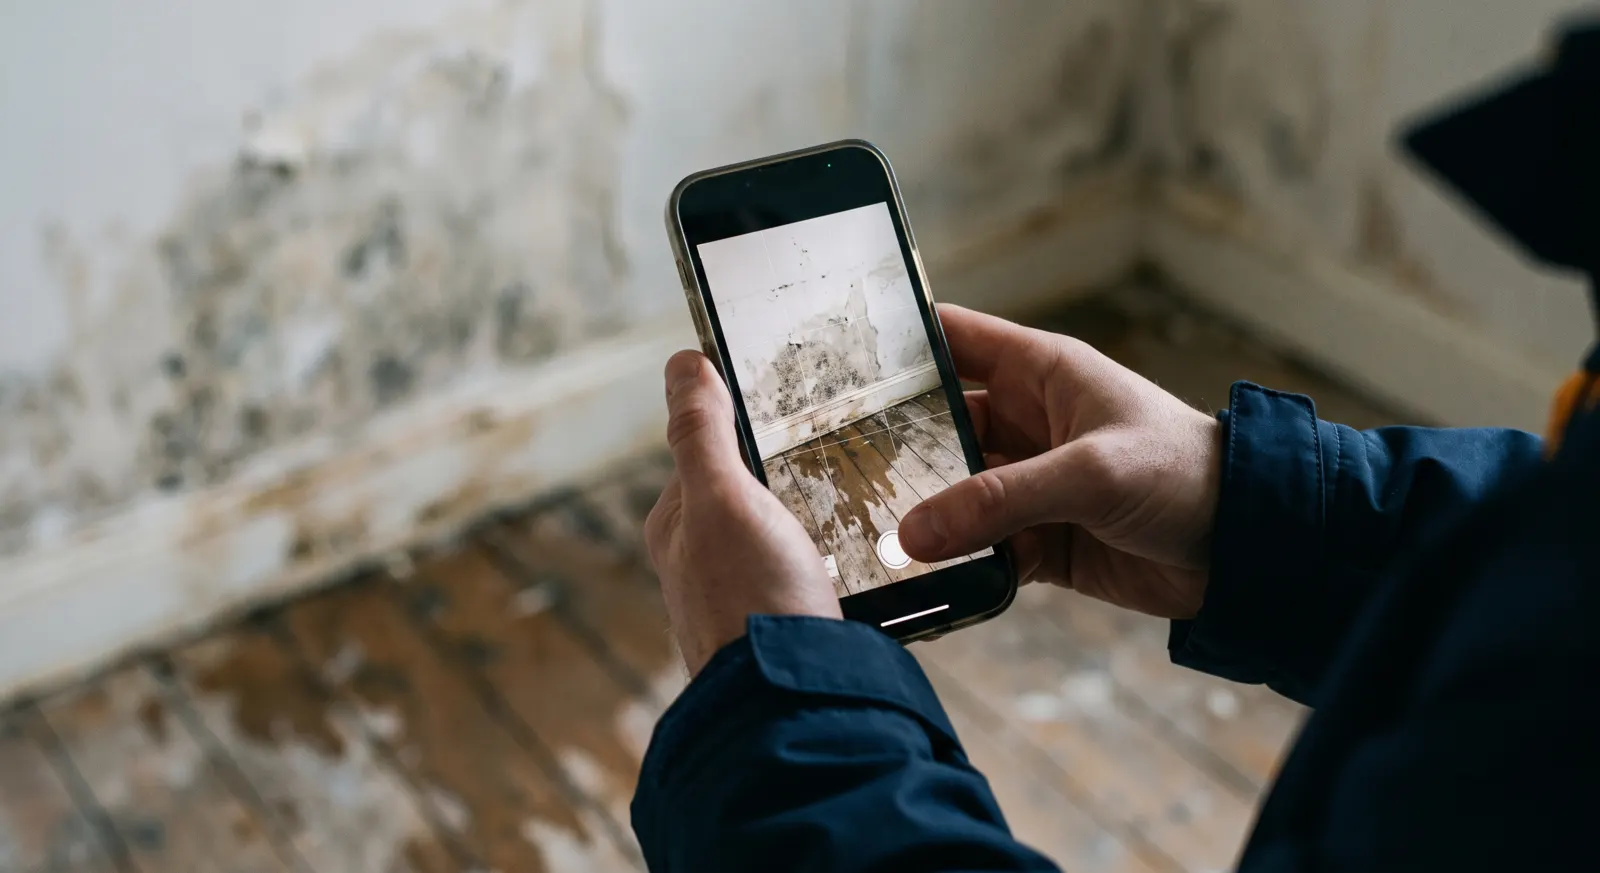
First: safety, then the source
Before any paperwork thinking - kill power to wet areas at the breaker, and stop the water at the fixture valve or the main. If it's sewage, keep people and pets away entirely. The claim can wait twenty minutes; these can't.
The eight steps
- ✓ 1. Stop the source - main valve, fixture valve, or breaker for appliance failures
- ✓ 2. Photograph and video everything BEFORE moving anything - wide shots, close-ups, serial numbers
- ✓ 3. Call your insurer's claim line - get the claim number and confirm emergency mitigation is authorized
- ✓ 4. Start mitigation fast - your policy requires preventing further damage
- ✓ 5. Keep every receipt - tarps, fans, and hotel nights can fall under your coverage
- ✓ 6. List damaged contents room by room - and don't discard anything until it's documented
- ✓ 7. Meet the adjuster armed - your photos plus the crew's moisture readings and scope
- ✓ 8. Get the scope in writing and read anything before you sign it
Step 2 is the one people skip
The instinct is to start hauling wet things out. Resist it for ten minutes. Adjusters reconstruct the loss from what you can show them - standing water, the failed pipe, the water line on the drywall, the soaked rug in place. Once it's cleaned up, you're describing; with photos, you're proving. Shoot more than feels reasonable.
Mitigation isn't optional - it's a policy duty
Every policy requires "reasonable steps to prevent further damage." Waiting for the adjuster before drying starts is the classic mistake - it reads as neglect, and the added damage from the wait can be excluded. Professional mitigation started the same day is exactly what the policy expects, and the crew's daily moisture readings become claim documentation - here's what that drying process looks like.
What not to do
Don't guess out loud about how long something's been leaking - "it's probably been dripping for months" turns a covered sudden loss into a maintenance denial, and you usually don't actually know. Don't throw away damaged materials before they're documented. Don't sign contracts or assignments under pressure at the door - a reputable crew's scope survives being read first. And don't wait to start drying.
If the claim gets disputed
Ask for a re-inspection with your documentation in hand - disputes are usually won on paper, and moisture logs beat memory. For large, genuinely stuck claims, licensed public adjusters exist to represent policyholders, and your state's insurance department takes complaints. Most claims never get there: sudden loss, fast mitigation, thorough documentation is the pattern that gets paid. What it costs and what's covered: the cost guide and the coverage guide.
Claim questions
Will filing a claim raise my rates?
It can factor into future pricing, which is why tiny losses sometimes aren't worth filing. For significant water damage the math often favors filing - a denied-later mold problem costs far more than a premium bump.
How long do I have to file?
Policies require 'prompt' notice, and some states and policies set hard deadlines. Practically: the sooner you report, the stronger the sudden-loss story. Report first, figure out details after.
Do I need multiple quotes before work starts?
Not for emergency mitigation - your policy expects you to stop the damage now, not collect bids while it spreads. Rebuild work afterward is where comparing quotes makes sense.
I already cleaned up - can I still claim?
Yes. File anyway: photos you took, receipts, water lines on the wall, and the crew's moisture readings can all reconstruct the loss. It's harder, not impossible.