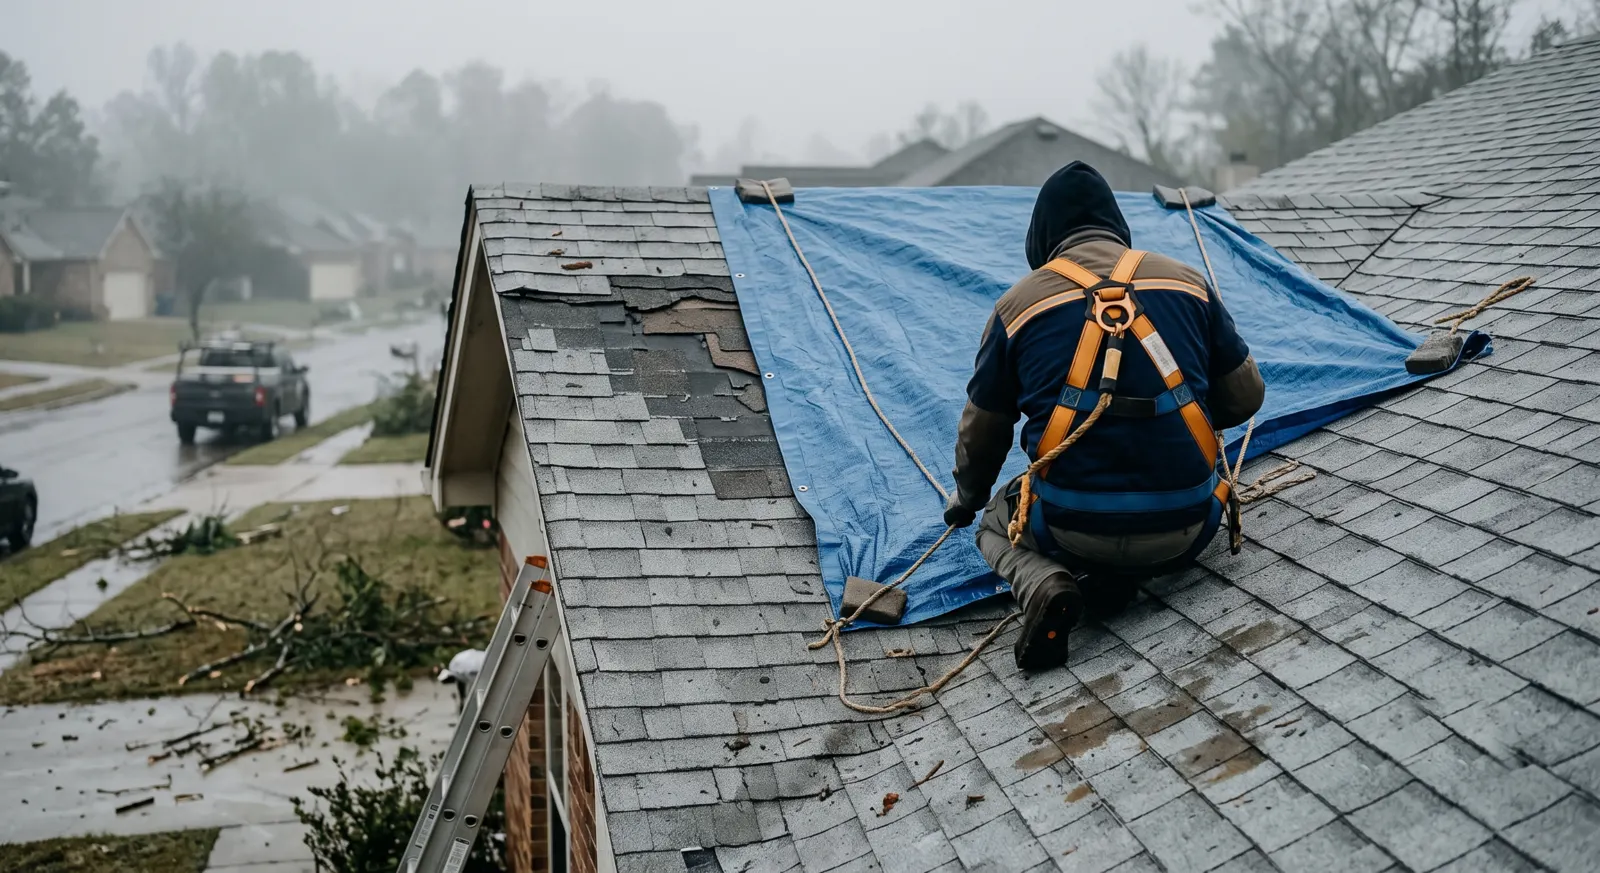
Signs you need a crew now
- Missing shingles, or daylight visible in the attic
- A broken window, door, or hole the rain can reach
- Water running down interior walls or pooling in the attic
- A tree or limb on the roof - stay out of that room
What happens when you call
-
Tell us what happened. 30 seconds - what's open to the sky and what's wet.
-
You're connected with a local restoration crew while you're on the line.
-
The crew confirms timing and your arrival time - tarping and board-up come first.
Why this one can't wait
An opening in the roof turns every following shower into a new loss - and your policy expects "reasonable mitigation," which means tarping and boarding fast, not waiting for the adjuster.
The crew secures the openings, photographs everything for the claim, extracts what already got in, and dries the structure before mold takes the storm's side.
Local to Hillsborough County
Tampa runs on daily summer thunderstorms and the hurricane cone - wind-driven rain through soffits and sliders, storm surge in the flood zones, and a water table that gives runoff nowhere to go. The CBS slab housing stock hides supply lines under concrete, and in this humidity wet drywall starts growing mold in 24 to 48 hours.
Florida policies may have a separate hurricane deductible. Whether it applies depends on the storm and the statutory hurricane period. Check your policy. Storm surge is flood insurance, not homeowner's, no matter what the hurricane did above the waterline. Everyday failures use your standard deductible.
Serving Tampa, St. Petersburg, Clearwater, Brandon, Riverview, Largo, and all of Hillsborough County.
Storm damage questions
Is storm damage covered by insurance?
Wind and hail damage - including the rain that enters through it - is standard homeowner's coverage. Rising water from outside is flood insurance, a separate policy. See the coverage guide.
Should I wait for the adjuster before touching anything?
Generally, no. Most policies require reasonable steps to prevent further damage. Photograph everything first, then, once it's safe, tarp and start drying. Keep receipts and records of what was done before the adjuster's visit.
Can I tarp the roof myself?
Not in the wet or the dark, and not after a storm has loosened things underfoot. Crews carry the gear and the fall protection - it's included in the mitigation the policy pays for.
Hurricane water came in - wind or surge?
It's the deciding question: wind-driven rain through damage is a homeowner's claim under the hurricane deductible; surge from the bay is flood insurance. Photograph water lines and entry points before cleanup.